By the Select Property editorial team
Last updated: 4 September 2026 · Checked against Office for National Statistics data to June/July 2026
Not financial, tax or investment advice. Values and rents can fall as well as rise, and tax treatment depends on your circumstances. Take advice from a UK-regulated solicitor and a qualified UK tax adviser before committing.
The average Manchester home cost £251,000 in June 2026 and the average flat £195,000, according to the Office for National Statistics. Average private rent reached £1,365 a month in July 2026. But a Singapore buyer pays about 8.6% of the price in stamp duty on top, and Savills forecasts 0.0% price growth for the North West in 2026.
Contents
- Is Manchester a good property investment?
- How much does a Manchester apartment cost?
- What rental yield can you actually get?
- Where to invest: an area-by-area guide
- The Oxford Road Corridor
- How to buy from Singapore
- Off-plan or completed?
- The risks
- Frequently asked questions
Is Manchester a good property investment?
Manchester’s average house price was £251,000 in June 2026, up 2.9% year on year, according to the Office for National Statistics, and average private rent reached £1,365 a month in July 2026. Savills forecasts 0.0% price growth for the North West in 2026, rising to 25.0% cumulatively by 2030. The income case is stronger than the capital case.
Savills attaches a caveat that matters more to off-plan buyers than to anyone else: “these forecasts apply to average values in the second-hand market. New build values may not move at the same rate.”
Manchester at a glance
| Metric | Figure | Source | As at |
|---|---|---|---|
| Average house price (all types) | £251,000 (+2.9% YoY) | Office for National Statistics | Jun 2026 |
| Average flat / maisonette | £195,000 (+1.1% YoY) | Office for National Statistics | Jun 2026 |
| Average private rent (all types) | £1,365/mo (+3.8%) | ONS Price Index of Private Rents | Jul 2026 |
| Gross yield (student/HMO postcodes) | 6.3%–7.3% | rentalyield.uk (Land Registry + VOA) | Q1 2026 |
| Gross yield (city-centre apartment) | 4.1%–5.1% (derived below) | Derived: ONS rent ÷ ONS price | 2026 |
| North West price forecast, 2026 | 0.0% | Savills Mainstream Forecasts | Jun 2026 |
| North West forecast, 2026–2030 | +25.0% cumulative | Savills Mainstream Forecasts | Jun 2026 |
| City-centre homes under construction | 8,023 units | Deloitte Manchester Crane Survey | 2026 |
How much does a Manchester apartment cost?
According to the Office for National Statistics, the average Manchester property sold for £251,000 in June 2026 and the average flat or maisonette for £195,000. A new-build city-centre apartment sits well above that: at Circle Square in M1, prices start from £290,000, about S$499,000.
Average prices by property type
| Property type | Price (GBP) | Price (SGD)* | Annual change |
|---|---|---|---|
| All property types | £251,000 | S$431,720 | +2.9% |
| Flats and maisonettes | £195,000 | S$335,400 | +1.1% |
| Terraced | £253,000 | S$435,160 | +4.4% |
| Semi-detached | £328,000 | S$564,160 | n/a |
| Detached | £478,000 | S$822,160 | n/a |
| First-time buyer average | £236,000 | S$405,920 | n/a |
GBP: ONS, Manchester (E08000003), June 2026. An annual change is shown only for the property types where we have read it on the ONS release; neither houses figure bears on the apartment case. * SGD at an assumed £1 = S$1.72, the rate implied by the S$499,000 / £290,000 pairing used across this site.
The £195,000 ONS flat average is a benchmark, not an M1 purchase price: it covers every flat in the city, including older ex-local-authority stock in M9, M11 and M40 trading well below city-centre pricing. New-build city-core stock costs more because land values in M1–M4 are the city’s highest, new blocks meet current building and cladding regulations that older stock does not, and amenity space has to be built and then paid for through the service charge.
What rental yield can you actually get?
Gross yields in Manchester’s student and HMO postcodes reached 7.3% in M11 and 7.1% in M9 in Q1 2026, on rentalyield.uk’s Land Registry and Valuation Office Agency data. A city-centre apartment is a different asset: derived from ONS prices and ONS rents, an M1 new build produces roughly 4.1%–5.1% gross, and materially less after charges.
How we derive the city-centre figure
rentalyield.uk does publish a figure for the city core, 4.0% for M1 on a median price of £292,951, but it applies one Manchester-wide median rent of £975 to every postcode, so its M1 number is not built on M1 rents. That is why we derive the city-centre range from two ONS series instead, and show the arithmetic.
| Assumption | Purchase price | Monthly rent | Annual rent | Gross yield |
|---|---|---|---|---|
| ONS Manchester flat average + ONS 1-bed rent | £195,000 | £998 | £11,976 | 6.14% |
| City-centre new-build entry + ONS 1-bed rent | £290,000 | £998 | £11,976 | 4.13% |
| City-centre new-build entry + ONS 2-bed rent | £290,000 | £1,227 | £14,724 | 5.08% |
Method: annual rent ÷ purchase price. Prices: ONS, Manchester, June 2026. Rents: ONS Price Index of Private Rents, Manchester, 2026.
The 6.14% belongs to the average Manchester flat and reads high precisely because that average includes cheap stock. ONS rents are city-wide across all property ages, so a well-specified M1 new build should let above them.
Gross yield vs net yield: the worked example
Gross yield is the figure you will usually be shown. It ignores every cost of ownership. Net yield is what actually reaches your account.
Scenario: a one-bed city-centre apartment at £290,000 (S$499,000), let at the ONS 1-bed rent of £998/month.
| Line | Amount (GBP) | Basis and assumption |
|---|---|---|
| Purchase price | £290,000 | Vita Living Circle Square North entry price (about S$499,000) |
| Gross annual rent | £11,976 | £998 × 12 (ONS Price Index of Private Rents, Manchester one-bed) |
| Gross yield | 4.13% | £11,976 ÷ £290,000 |
| Less: letting and management fee | −£1,150 to −£1,868 | Full management at 8%–13% of rent plus VAT, which is 9.6%–15.6% including VAT at the 20% standard rate. Range taken from the published fee schedules of twelve named Manchester agents, August 2026 |
| Less: void allowance | −£479 | 4% of rent, about two weeks a year. Our assumption, not a market figure |
| Less: repairs and renewals allowance | −£300 | Our assumption for a furnished new build |
| Less: annual service charge | −£2,000 to −£2,600 | Indicative range for a Manchester city-centre one-bedroom apartment of 500–635 sq ft |
| Less: annual ground rent | £0 | Peppercorn, fixed by the Leasehold Reform (Ground Rent) Act 2022. See below |
| Net annual income | £6,729 to £8,047 | Gross rent less the four cash deductions above |
| Net yield | 2.32% to 2.77% | Net income ÷ £290,000 |
Pre-tax, unleveraged, and before stamp duty and acquisition costs. Every assumption is stated in the table. Buildings insurance is billed inside the service charge in most Manchester blocks but separately in some, which adds roughly £300 a year where it happens; ask which applies before you model it.
Why ground rent is nil, and why most pages still show it as a cost
Under the Leasehold Reform (Ground Rent) Act 2022, any regulated lease granted on or after 30 June 2022 may charge an annual rent of one peppercorn and no more, with gov.uk setting penalties of £500 to £30,000 per breach and a refund order on top. Vita Living Circle Square North completes in 2027, so its leases are granted after commencement and fall squarely inside the Act.
Most competitor pages still carry a ground rent line of £250 to £500 in their yield sums. They are not inventing it: a large share of Manchester’s “new-build” stock on resale today was granted a lease in 2019 to 2021, before the Act commenced, and those leases still carry a money ground rent. The Act bites on the date the lease was granted, not on how new the building looks. A new lease granted to you is a peppercorn; an assignment of a 2019 lease is not, and you inherit whatever that lease says.
Sensitivity: the two variables that move the answer
Two inputs are ranges rather than single figures, so we publish the grid rather than pick a number inside it. Each cell is arithmetic on the table above, not a quoted market figure.
| Management fee | Service charge £2,000 | Service charge £2,300 | Service charge £2,600 |
|---|---|---|---|
| 8% + VAT (£1,150) | £8,047 · 2.77% | £7,747 · 2.67% | £7,447 · 2.57% |
| 10.5% + VAT (£1,509) | £7,688 · 2.65% | £7,388 · 2.55% | £7,088 · 2.44% |
| 13% + VAT (£1,868) | £7,329 · 2.53% | £7,029 · 2.42% | £6,729 · 2.32% |
Net annual income · net yield on £290,000. The 10.5% row is the midpoint of the 8%–13% range, not a quoted rate. Void and repairs allowances are held constant at £479 and £300.
Note what the grid shows: the service charge and the management fee together move the answer by only about 0.45 of a percentage point. On a page like this, the temptation is to present that spread as uncertainty. It is not. The honest reading is that a city-centre one-bedroom at this price lands in the low-to-mid 2% range on almost any reasonable combination of the two.
A two-bedroom apartment carries the higher ONS rent of £1,227 per month, but it also costs more than the £290,000 one-bedroom entry price. We have deliberately not published a two-bedroom net yield, because dividing two-bedroom rent by a one-bedroom price would overstate the return. Once the two-bedroom entry price is confirmed, this table gains a second column computed on the same formula.
On these assumptions a city-centre Manchester one-bedroom apartment nets between 2.3% and 2.8% before tax. Size the decision on that number, not the advertised one.
Why headline “8% yields” usually aren’t city-centre apartments
Those yields come from M11 (7.3%), M9 (7.1%), M18 (7.1%), M40 and M8 (6.4%) and M12 (6.3%) on rentalyield.uk’s Q1 2026 data: terraced houses and HMOs in Openshaw, Harpurhey, Gorton and Cheetham Hill. The yield is high because the price is low, and it brings HMO licensing, higher turnover and thinner resale liquidity. Averaging those postcodes with M1 is not arithmetically wrong; it is simply not the yield on the apartment you are being shown.
Where to invest: an area-by-area guide
Three areas suit a Singapore buyer purchasing remotely: the city core (M1–M3), for professional tenants and the deepest resale market; Ancoats and the Northern Quarter (M4), for the same tenant in converted stock; and Salford Quays (M50), which published a 5.4% gross yield in Q1 2026 on rentalyield.uk data. The student belt is not one of them.
| Area | Postcode | Published gross yield (Q1 2026) | Tenant profile | Suits a remote owner? |
|---|---|---|---|---|
| City centre core | M1, M2, M3 | Not published (derived 4.1–5.1%) | Professionals, corporate lets | Yes: salaried tenants on single assured shorthold tenancies, and the deepest resale market, bought at a lower yield and a higher service charge |
| Ancoats / Northern Quarter | M4 | Not published | Creative and tech professionals | Yes: mills converted to widely varying standards, so a survey you cannot attend matters more here than anywhere else |
| Salford Quays / MediaCity | M50, M5 | 5.4% (M50), 5.4% (M5) | Media, broadcast, corporate | Yes: the strongest published yields of the six, on a real employment base; check block-level rent competition, not the area average |
| Student belt | M14, M15 | Not published | Undergraduates, HMO sharers | No: an HMO licence, per-room tenancies, an annual summer void and hands-on management that does not travel |
| Victoria North | M4, M40 | 6.4% (M40) | Mixed, regeneration-stage | Caution: the city’s largest regeneration site, so a long build-out and thin comparable evidence for valuation and resale |
| Old Trafford | M16 | Not published | Mixed professional / family | Caution: fragmented stock |
rentalyield.uk, Q1 2026 data read on 21 August 2026, from Land Registry sold prices and VOA rents. Read the spread with care: it applies a single Manchester-wide median rent of £975 to every Manchester postcode, and the Salford median of £890 to M5 and M50. The gap between these rows is therefore a difference in purchase price, not a difference in achievable rent. It publishes 4.0% for M1 and 5.1% for M14; it does not publish M3, M4 or M15, and we have not substituted an estimate.
The Oxford Road Corridor
The Oxford Road Corridor generates around £5bn in GVA a year. It hosts more than 104,000 employees and 86,000+ students, including 22,000+ international and 42,000+ studying STEM subjects, according to oxfordroadcorridor.com (as at 2026). It also accounts for 48% of Manchester’s life-sciences businesses and draws 4.7 million visitors a year.
That concentration is the demand side of a city-centre tenancy: two universities, a teaching hospital campus and a life-sciences cluster on one mile-long spine, and Manchester’s universities and graduate housing retain an unusually high share of graduates afterwards as professional tenants. The corporate arrivals point the same way, from Amazon’s £3bn investment into Manchester and JP Morgan doubling its Manchester business to 7,000 civil service roles relocating from London.
Circle Square
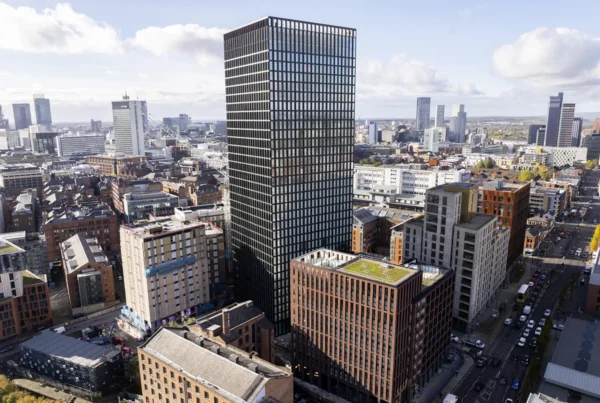
Circle Square is the Corridor’s flagship neighbourhood: a £750m, 2.25 million sq ft development on the former BBC Broadcasting House site, delivered by Bruntwood SciTech and Vita Group, with 1,700+ homes and 1.2 million sq ft of workspace. What makes it unusual is that the employers are inside the scheme.
PUMA relocated its UK headquarters from London to Circle Square, Auto Trader committed to the neighbourhood and Havas opened offices there, alongside the Information Commissioner’s Office. On-site employment is the shortest route to a tenant. The residential element includes Vita Living Circle Square North, a 35-storey tower of 417 furnished apartments from studios to three beds, the stock this guide’s arithmetic is modelled against.
How to buy a Manchester apartment from Singapore
A Singapore buyer can complete a Manchester purchase entirely remotely; no UK visit is legally required. The number to plan around is tax: on a £290,000 apartment, a non-resident buying an additional dwelling pays £24,800 in stamp duty, an effective 8.55%, under the rates published at gov.uk.
The step-by-step process
- Reserve the unit on a reservation fee, typically £500 to £2,000 on UK new builds.
- Instruct a UK solicitor for conveyancing, searches and the stamp duty return, appointed independently of the seller.
- Complete remote ID and AML checks: certified passport, proof of address, source of funds. Remote purchases most often stall here.
- Exchange contracts on the 10% deposit. At Vita Living Circle Square North: 10% down, nothing further until June 2027. Exchange is the binding point.
- Pay staged payments per the contract.
- Complete: balance paid, the stamp duty return filed and the tax paid within 14 days of the effective date, title registered.
- Hand over to letting management: tenancy, inventory, deposit protection.
You do not need a UK bank account to complete, but you will need one, or a UK-facing multi-currency account, to receive rent and pay the service charge.
What it costs on top of the purchase price
Stamp Duty Land Tax on £290,000 (non-UK-resident, additional dwelling):
| Band | Rate | Tax |
|---|---|---|
| £0 – £125,000 | 0% | £0 |
| £125,001 – £250,000 | 2% | £2,500 |
| £250,001 – £290,000 | 5% | £2,000 |
| Standard SDLT | £4,500 | |
| Additional dwelling surcharge | 5% of £290,000 | £14,500 |
| Non-UK-resident surcharge | 2% of £290,000 | £5,800 |
| Total SDLT | 8.55% effective | £24,800 (≈ S$42,656) |
gov.uk, SDLT residential rates. The additional-dwelling surcharge rose to 5% on 31 October 2024; the 2% non-resident surcharge applies if you were not in the UK for at least 183 days in the 12 months before purchase.
The same stamp duty stack applies to any UK purchase, not just Manchester; our UK property investment guide for Singapore investors works it at other price points and sets it against Singapore ABSD.
| Other acquisition costs | Amount | Basis |
|---|---|---|
| Conveyancing / legal fees | £1,200–£2,000 plus VAT (£1,440–£2,400 including VAT) | Indicative range for a mainstream conveyancer on a £290,000 leasehold new build. A leasehold specialist or City firm runs higher |
| Searches, Land Registry and AML | about £650–£1,000 | HM Land Registry registration £330; Manchester City Council local authority search (LLC1 + CON29) about £74.50 including VAT, indicative: the council’s own fee page could not be opened to confirm it, so treat it as a guide and ask your solicitor for the current figure; full search pack £250–£450; AML and ID checks £10–£36 per person, plus £50–£150 if ID must be notarised in Singapore |
| FX conversion cost | roughly 0.3%–1.0% of the sum converted with a specialist provider or a negotiated bank rate, against roughly 1%–3% on an unnegotiated Singapore bank board rate | Indicative. On £290,000 that is about £870–£2,900 against about £2,900–£8,700 |
| Indicative all-in acquisition cost | about £316,900–£319,200, plus the FX cost of converting the funds | £290,000 + £24,800 SDLT + the legal and disbursement ranges above. The top of the range allows for the new-build conveyancing supplement and the Building Safety Act review that a leasehold apartment attracts |
Tax as an overseas landlord
Under the Non-Resident Landlord Scheme, your letting agent (or the tenant, if there is no agent) must deduct basic-rate UK tax from your rent at source unless HMRC approves gross payment, applied for on form NRL1. File it before the first tenancy starts; you then file UK Self Assessment annually. When you sell, Non-Resident Capital Gains Tax applies to UK residential disposals by non-residents at 18% and 24% from 6 April 2026, with an annual exempt amount of £3,000 for 2026/27, and the disposal must be reported to HMRC and the tax paid within 60 days of completion, per gov.uk, even where there is no tax to pay. Making Tax Digital thresholds and entitlement to the £12,570 UK personal allowance both turn on facts specific to you, and our UK property investment guide for Singapore investors sets both out in full.
Confirm your own position with a qualified tax adviser before you commit. Everything above is the general rule for an overseas landlord; none of it can tell you what applies to you. Your nationality, your UK residence history, whether you buy in your own name or through a company, whether there is a mortgage and what other UK income you have all move the answer, and the rules themselves change from one Budget to the next. Have a qualified UK tax adviser confirm the numbers for your circumstances, and a Singapore tax adviser where your Singapore position is affected, before money is committed.
Off-plan or completed?
Off-plan secures a lower entry price and a staged payment schedule (at Circle Square, 10% down with nothing further until June 2027), but you own a contract, not a flat, until completion. A completed apartment produces rent immediately and can be viewed and surveyed. Off-plan carries build, delay and valuation risk a completed purchase does not.
| Off-plan new build | Completed resale | |
|---|---|---|
| Entry price | Typically below completed pricing | Market price |
| Payment schedule | Staged: e.g. 10% now, balance on completion | Full price at completion, weeks away |
| Capital at risk pre-completion | Deposit only | None before exchange |
| Build / delivery risk | Yes: delay or non-completion possible | None |
| Time to first rent | 12 to 36 months from reservation, most often 18 to 24 (indicative) | Weeks |
| Can you inspect it? | No: plans and show units only | Yes, plus a survey |
| Resale before completion | Difficult; often contractually restricted | N/A |
| Valuation risk at completion | Yes: a down-valuation is your problem | Known at purchase |
| Typical incentives | Furniture packs, fee contributions, rental guarantees | Rare |
The risks: what could go wrong
Savills forecasts 0.0% price growth for the North West in 2026 and −2.0% for the UK, while Deloitte’s Manchester Crane Survey counts 8,023 city-centre homes under construction, with around 5,500 completions forecast for 2026 against 3,422 in 2025. Flat prices and rising supply in the same year is the central risk.
- Supply. A 60% jump in completions lands in one year. Where your apartment competes with dozens of near-identical units in one postcode, supply shows up in rents and voids first, prices second.
- Flat capital values in 2026. The forecast is 0.0%, with the caveat that new build may not track the second-hand market at all. Underwriting this on two-year growth is underwriting the wrong thing.
- Service-charge inflation. The largest controllable variable in the net-yield table, rising sharply across UK new-build blocks. The Property Institute’s 2026 index puts buildings over 18 metres at £4,447 per leaseholder against £2,418 for buildings under 11 metres, an 84% premium, and calls building height the single strongest predictor of the charge in its dataset. Ask for the service-charge history of the developer’s completed schemes, not just the year-one budget. There is a lending angle too: Hamptons reports that 37% of flats now carry a service charge above 1% of value and that lenders are tightening against them. At £290,000 a £2,300 charge is 0.79%, inside that threshold, but it is a pre-offer check rather than an afterthought.
- Leasehold itself, which is the bigger and better-evidenced risk. Ground rent is a peppercorn on your lease, but leasehold still costs you at the exit. On Connells Group research covering agreed sales in England, leasehold transactions took 155 days to exchange against 97 days for freehold in April 2026, a 58-day gap and the widest on record, against a pre-Covid gap of 13 days. And 43% of agreed leasehold sales fell through in 2025, against 36% for freehold. When you come to sell, you are selling into a slower market with a materially higher chance of the buyer walking. Price that into the hold period, not into the yield.
- Leasehold reform is still moving. The Leasehold and Freehold Reform Act 2024 received Royal Assent but its main valuation provisions, including the abolition of marriage value, are not yet commenced. The Commonhold and Leasehold Reform Bill of January 2026 is a draft, not law. Both are directionally good for leaseholders, and neither can be relied on by a buyer today.
- Currency. Over a five- to ten-year hold, GBP/SGD movement can exceed the entire capital gain. Entry and exit are the exposed cash flows, and the largest.
- Resale liquidity. Blocks with heavy investor ownership can see several identical units listed at once, compressing what a hurried seller achieves.
- Tax. About 8.6% stamp duty on entry and Non-Resident CGT on exit mean this needs a long hold.
Frequently asked questions
Is Manchester a good place to invest in property?
Stronger for income than for near-term capital growth. Average rent reached £1,365 a month in July 2026 (ONS), and Savills forecasts 25.0% cumulative North West growth to 2030, but 0.0% in 2026. Treat it as a long-hold income asset.
Are property prices falling in Manchester?
Not currently. According to the Office for National Statistics, Manchester’s average price rose 2.9% in the year to June 2026, to £251,000; flats rose 1.1%. Savills forecasts 0.0% for the North West in 2026 and −2.0% for the UK. Flat, not falling.
Is Manchester a good investment in 2026?
For a five-year-plus horizon, yes; for a two-year hold, no. Savills forecasts 0.0% North West growth in 2026, then 3.5% in 2027 and 6.5% a year to 2030. With about 8.6% stamp duty on entry, a short hold does not recover its costs.
Is it worth buying an apartment in Manchester?
It depends on net yield, not gross. A city-centre apartment yields roughly 4.1%–5.1% gross on ONS price and rent data, but the service charge, management fees and voids cut a one-bedroom to about 2.3%–2.8% net. Ground rent on a new lease is a peppercorn by statute.
Do you pay ground rent on a new-build Manchester apartment?
No. Under the Leasehold Reform (Ground Rent) Act 2022, any lease granted since 30 June 2022 carries a ground rent of one peppercorn, effectively nil, and gov.uk sets penalties of £500 to £30,000 for charging more. Vita Living Circle Square North completes in 2027, so its leases fall under the Act.
How much is the service charge on a Manchester city-centre apartment?
Budget £2,000 to £2,600 a year for a one-bedroom, an indicative range for city-centre stock. The Property Institute’s 2026 index puts buildings over 18 metres built since 2000 at £3,706 per leaseholder across all unit sizes, and a one-bedroom sits below that because charges are apportioned by floor area.
Is Manchester expensive to buy property?
Not by UK standards. The average Manchester property cost £251,000 in June 2026 and the average flat £195,000, according to the Office for National Statistics. Greater Manchester averaged £281,801 over 12 months on Rightmove data.
What is the current trend of property prices in Manchester?
Rising slowly, expected to flatten. ONS recorded +2.9% in the year to June 2026 across all types, but only +1.1% for flats and maisonettes, the segment that matters to apartment investors. Savills then forecasts 0.0% for the North West in 2026.
Is it a good time to buy a house in Manchester?
For income, the entry point is reasonable: rents rose 3.8% in the year to July 2026 (ONS) while flat prices rose only 1.1%. For capital growth, 2026 is forecast flat. Buying now makes sense if you are underwriting rent, not resale.
Is Manchester still booming?
The economy is; the housing market is consolidating. Deloitte’s Crane Survey records 8,023 city-centre homes under construction and around 5,500 completions forecast for 2026. Construction is booming, which is precisely why prices are forecast flat.
Next steps
If you are weighing a specific apartment rather than the market generally, the next step is the unit mix and pricing. Vita Living Circle Square North is a 35-storey, 417-apartment tower in Circle Square, M1, from £290,000 (about S$499,000), with a 10% deposit and nothing further until June 2027. Review the floorplans by unit type, see the location, or speak to the team in Singapore about the figures, including the service charge. For the wider picture, see our guide to UK property investment for Singapore investors.
General information only, not financial, tax or investment advice. Take independent advice from a UK-regulated solicitor and a qualified tax adviser before purchasing.