By the Select Property editorial team
Last updated: 30 August 2026 · Law checked against gov.uk guidance on 21 August 2026
Not financial, tax or investment advice. Rents and values can fall as well as rise, and tax treatment depends on your circumstances. Take advice from a UK-regulated solicitor and a qualified UK tax adviser before committing.
A Manchester city-centre apartment yields roughly 4.1%–5.1% gross on Office for National Statistics data, and about 2.32%–2.77% net before tax on our worked example. Two things you will be told wrongly. Stamp duty on an additional home is 5%, not 3%, and a non-UK-resident pays a further 2%, so £24,800 on a £290,000 flat, an effective 8.55% under the rates published at gov.uk. And section 21 no-fault eviction no longer exists.
Contents
- Is Manchester good for buy-to-let?
- Gross yield versus what actually reaches your account
- Where the yields are, in one table
- What a UK buy-to-let mortgage requires from a non-resident
- The law changed in 2026, and the search results have not caught up
- Managing a Manchester apartment from Singapore
- What else could go wrong
- Frequently asked questions
- Next steps
Is Manchester good for buy-to-let?
For income, yes. According to the Office for National Statistics, the average Manchester one-bedroom let for £998 a month in July 2026 and the average across all property types for £1,365, up 3.8% on the year. For capital growth, no: Savills forecasts 0.0% price growth for the North West in 2026.
Rent is the reason to do this, so it is worth seeing the whole table rather than the headline figure. The row that matters to an apartment buyer is not the one most guides quote.
| Property size, Manchester | Average monthly private rent, July 2026 |
|---|---|
| One bedroom | £998 |
| Two bedrooms | £1,227 |
| Three bedrooms | £1,425 |
| Four or more bedrooms | £2,005 |
| Flat or maisonette | £1,142 |
| All property types | £1,365 |
Office for National Statistics, Price Index of Private Rents, Manchester local authority (E08000003), July 2026, released 19 August 2026. Read off the ONS local housing tool on 21 August 2026.
The figure to model an apartment against is £1,142, the flat and maisonette average, which sits £223 below the all-property-types number most pages lead with. It is also a city-wide average covering stock of every age, so a well-specified new build in M1 should let above it. Our Manchester property investment guide for Singapore buyers sets these rents against Manchester prices and the Savills forecast in full.
Gross yield versus what actually reaches your account
A Manchester city-centre apartment produces roughly 4.1%–5.1% gross, and about 2.32%–2.77% net on the net-yield worked example in that guide: a £290,000 one-bedroom let at the ONS rent of £998 a month, after management, voids, repairs and the service charge. That net figure is still before any UK tax.
Four deductions do the damage, and only one of them is the one buyers expect.
- Letting and management. 8%–13% of rent plus VAT in Manchester, which is 9.6%–15.6% including VAT at the 20% standard rate.
- Voids. Rent stops between tenancies; the service charge does not.
- Repairs and renewals. Small on a new build, not nil, and higher on a furnished let.
- The service charge, indicatively £2,000–£2,600 a year on a city-centre one-bedroom, and on these numbers the single largest deduction, larger than the management fee.
- Ground rent, which is nil. Under the Leasehold Reform (Ground Rent) Act 2022, a regulated lease granted on or after 30 June 2022 may charge only a peppercorn. Most competitor pages still carry a £250–£500 ground rent line, because much resale stock sits on pre-2022 leases.
The arithmetic and a sensitivity grid are on the main guide and we are not repeating them. What that example stops short of is the layer that decides how much you actually see.
The deduction the worked example leaves out, which is tax
Under the Non-Resident Landlord Scheme, your letting agent must deduct basic-rate UK tax from the rent at source unless HMRC has approved gross payment, applied for on form NRL1. A Singapore owner who has not filed NRL1 before the first tenancy begins receives rent net of basic-rate tax from month one, and recovers the difference later through Self Assessment. That is a working-capital problem as well as a tax one, because the service charge and any mortgage payment fall due on the full amount while the rent arrives reduced.
We have deliberately not published a post-tax net yield percentage: entitlement to the UK personal allowance turns on nationality and status rather than on where you live, and is not settled for a Singapore national. The rates, the personal-allowance question and the capital gains position on sale are set out at primary source in our guide to UK property tax and financing for Singapore buyers.
Where the yields are in Manchester, in one table
On rentalyield.uk’s Land Registry and Valuation Office Agency data for Q1 2026, read on 21 August 2026, the highest published Manchester yields are M11 at 7.3% and M9 at 7.1%. Both are terraced and ex-local-authority stock, not city-centre apartments. M1, the city core, publishes 4.0% on a median price of £292,951.
| Postcode | Area | Published gross yield, Q1 2026 | What the stock is | Works from Singapore? |
|---|---|---|---|---|
| M11 | Openshaw | 7.3% | Terraced houses, low prices | No. Hands-on stock, thin resale market |
| M9 | Harpurhey | 7.1% | Terraced and ex-local-authority | No. Same reasons |
| M40 | Miles Platting, Newton Heath | 6.4% | Terraced, regeneration edge | Caution. Thin comparable evidence |
| M50 | Salford Quays, MediaCity | 5.4% | Apartments, real employment base | Yes. Check block-level rent competition |
| M5 | Salford, Ordsall | 5.4% | Mixed apartments and terraces | Yes, with stock selection |
| M14 | Fallowfield, the student belt | 5.1% | Student houses and HMOs | No. See below |
| M1 | City centre core | 4.0% | New-build apartments | Yes. Single tenancies, deepest resale market |
rentalyield.uk, Q1 2026, built from HM Land Registry sold prices and Valuation Office Agency rents. Each postcode page was read on 21 August 2026 and the figures are shown to one decimal place at source.
One caveat matters more than the ranking. That dataset takes rents at local authority level, so every Manchester district above is calculated on the same city-wide median rent of £975 a month, and every Salford one on £890. The gaps between the rows are price differences, not rent differences: M11 scores 7.3% because its median price is £160,000, not because its tenants pay more.
The student belt is the usual source of high headline yields and usually the wrong purchase from Singapore: an HMO licence, per-room tenancies, an annual summer void and hands-on management that does not travel, even though Manchester’s student population keeps driving construction. A fuller postcode-by-postcode analysis is a separate piece of work.
What a UK buy-to-let mortgage requires from a non-resident
The rent caps the loan before the loan-to-value ceiling does. A buy-to-let lender tests projected rent against mortgage interest, and on a one-bedroom apartment that test usually binds first. We are not publishing a market-wide maximum loan-to-value, a minimum deposit or a non-resident rate premium, because no reliable published figure exists for the market as a whole.
What generalises is the mechanism, not the numbers.
- The interest cover test decides the loan. Longer fixed-rate products are commonly tested at the rate you actually pay, shorter ones at a higher stress rate, so on identical rent a five-year fix can support a materially larger loan than a two or three-year one.
- Minimum loan sizes exist, and they block the opposite strategy to the one people worry about: you often cannot borrow a small amount, so a deliberately low-geared purchase is unavailable.
- The building is assessed as well as the borrower. Storey count, floor area, EPC rating and unexpired lease length can each bind before the loan-to-value does.
One named lender’s published criteria, and a worked example of what they cap the loan at on a £290,000 Manchester apartment, are in our UK property tax and financing guide. Anything you are told about Singapore bank lending against UK property should come from your own relationship manager, in writing and dated.
The law changed in 2026, and the search results have not caught up
Under the Renters’ Rights Act, gov.uk’s landlord guidance published 1 May 2026 states that “you cannot evict tenants using the section 21 process”. If you need to sell, you “cannot evict your tenants for this reason within the first 12 months of a tenancy”, and after that you need a section 8 ground, commonly with four months’ notice.
The Act received Royal Assent on 27 October 2025. Everything below is from that same gov.uk guidance, read on 21 August 2026, and applies to England.
- Tenancy type. “All existing assured shorthold tenancies (ASTs) will change to assured periodic tenancies and new tenancies will be assured periodic tenancies.” They run “on a rolling basis, for example, monthly”, and a tenancy agreement cannot carry an end date.
- Possession. Section 21 is gone. You need a legal ground and a section 8 notice, and “in many cases this is 4 months” of notice, shorter for some grounds.
- Selling or moving in. Neither ground is available in the first 12 months of a tenancy.
- Rent increases. Once a year only, on Form 4A with at least two months’ notice, and the tenant can challenge an increase above the open market rent. Rental bidding is banned: you publish an asking rent and cannot accept offers above it.
- Pets. A tenant can ask, and you can refuse only with a valid reason.
- Arrears. The court only has to grant possession where the tenant owes three months’ rent. Below that, it may let them stay.
- Rent repayment orders. The maximum has risen from one to two years’ rent.
- Deposits. Possession depends on the deposit having been protected in a government-approved scheme. An unprotected deposit blocks the order.
None of this makes Manchester a bad investment. It makes it a longer-dated one.
What this does to your exit
Do the arithmetic in plain terms. Twelve months in which the sale ground is not available, plus a notice period that is commonly four months, is up to about 16 months between deciding to sell with vacant possession and being able to start. Rightmove puts the North West’s time to find a buyer at 57 days and time to complete at 152, a total time to move of 209 days, and that clock only starts afterwards.
The useful response is not to avoid the asset. It is to plan the exit at the tenancy level from the first tenancy rather than at the point you decide to sell.
What is in the Act but not yet running
The Act also provides for a Private Rented Sector Database, with registration becoming a precondition of using certain possession grounds, a PRS Landlord Ombudsman that all private landlords in England will be required by law to join, the Decent Homes Standard applied to private renting, Awaab’s Law, and a prohibition on taking large amounts of rent in advance. The gov.uk pages we read give no commencement dates for these, and we are not going to invent one. Expect a further compliance layer and a probable small annual per-property ombudsman fee.
Managing a Manchester apartment from Singapore
Full management in Manchester runs 8%–13% of rent plus VAT, which is 9.6%–15.6% including VAT at the 20% standard rate. That range comes from the published fee schedules of twelve named Manchester agents read in August 2026, not from a market survey, because no authoritative survey of what UK landlords actually pay their agents exists.
Three things cost more than the headline percentage suggests.
The VAT trap. Some agents headline “plus VAT”, some quote inclusive, some publish both. A landlord comparing “12% plus VAT” at one agent with “12% including VAT” at another is comparing two figures 44% apart. Force every quote to an including-VAT number before you compare anything.
The fees outside the percentage. Tenant-find and setup charges of one month’s rent plus VAT are common. On a £1,000 a month flat, that one fee can exceed a whole year of the difference between an 8% and a 13% management rate, which is why comparing management percentages alone is the wrong comparison. Inventory, renewal, check-out and vacant-property inspection fees are charged on top, and the last matters more to an overseas owner than a local one, because you cannot walk past the building yourself.
Who pays the service charge during a void. You do. It is the largest line in the net-yield sum and it does not pause when the rent does, which is what turns a two-month void into a measurable hit on the year.
What else could go wrong
The risks specific to being an overseas landlord are compliance and information, not the market. Supply, the 2026 price forecast and leasehold exit friction are set out with their evidence in the risks section of our Manchester guide.
- Compliance drift. The Act’s remaining measures land on a timetable nobody has published, and each is a cost. On energy efficiency, gov.uk’s guidance updated 5 May 2026 still sets the minimum at EPC band E; band C by 2030 appears there as an aim the government has committed to exploring, not a requirement.
- Licensing. Selective licensing operates in parts of Manchester, and whether your building sits inside a designated area changes both your cost and your legal position. We could not open Manchester City Council’s pages on 21 August 2026, so we print no ward list and no fee. Check the council’s own scheme map against the exact address.
- Management and service-charge inflation, compounding on the same asset and hitting the same line of the same spreadsheet.
- Information risk. Most of what ranks for this subject in Singapore is published by companies selling the property, and a widely repeated stamp duty figure in Google’s own AI summary of it is out of date: it still describes a 3% surcharge, when the additional-dwelling rate rose to 5% on 31 October 2024 and a non-resident pays 2% on top. Date-check every number you are given, including every number here.
Frequently asked questions
Is Manchester good for buy-to-let?
For income, yes; for a quick exit, no. Average Manchester rent was £1,365 a month in July 2026 and a one-bedroom £998, according to the Office for National Statistics. But a city-centre apartment nets roughly 2.32% to 2.77% before tax on our worked example, and a non-resident pays 8.55% in stamp duty on entry.
Is buy-to-let still worth it in the UK?
Only over a long hold, on these numbers. A non-resident pays £24,800 of stamp duty on a £290,000 flat, an effective 8.55% under the rates at gov.uk, before any rent arrives, and management costs 9.6% to 15.6% of rent including VAT. A net yield in the low-to-mid 2% range does not recover that in two or three years.
Is buy-to-let a good idea in the UK?
It is a more regulated business than it was. Under the Renters’ Rights Act, gov.uk’s landlord guidance published 1 May 2026 states that you cannot evict tenants using the section 21 process, that tenancies are now periodic with no end date, and that you cannot evict in order to sell within the first 12 months of a tenancy.
Why are foreigners snapping British buy-to-let?
Mainly the yield gap against home markets, plus sterling. But two things have made the answer worse since 2024: the additional-dwelling stamp duty surcharge rose to 5% on 31 October 2024, per gov.uk, and section 21 no-fault eviction has since been abolished. A non-UK-resident also pays a further 2% surcharge and has rent taxed at source.
For whether prices are falling, see the Manchester property investment guide, which answers it on ONS and Savills data.
Next steps
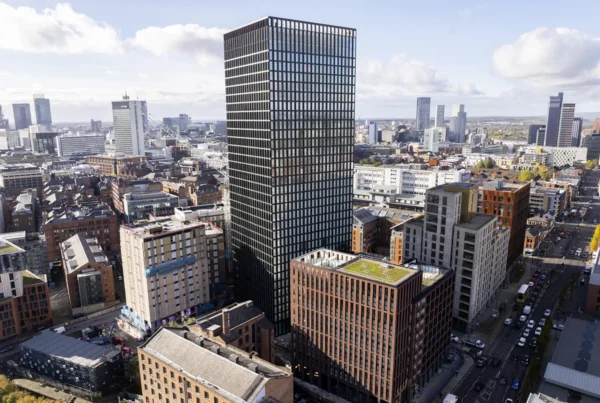
If you are underwriting a specific apartment rather than the market, the next step is the unit mix and the service charge. Vita Living Circle Square North is a 35-storey, 417-apartment tower in Circle Square, M1, from £290,000. Review the floorplans by unit type, or speak to the team in Singapore. For the wider market, see our Manchester property investment guide and our UK property investment guide for Singapore investors.
General information only, not financial, tax or investment advice. Rents, values and currency can move against you, and you may get back less than you invested. Take independent advice from a UK-regulated solicitor and a qualified UK tax adviser before purchasing.